you have $10,000 sitting in a savings account, and after a full year, your bank has paid you enough interest to buy a cup of coffee. That’s roughly what happens with a basic 0.30% APY savings account — around $30 a year. Now picture the same $10,000 earning closer to $400 a year at a competitive rate. Same amount of money, same FDIC protection, dramatically different outcome. The only thing that changed is where the money sits.
The difference is exactly what brings most readers to this article. If you bank with Stock Yards Bank & Trust or you should check with the banks before opening a new account. So you’ve probably wondered if one of its song accounts can actually compete with the high-yield accounts offered for online advice. The short answer is that the standard statement of the stage is the bank. The short answer: Stock Yards Bank’s standard Statement Savings account is a traditional, branch-based savings product, and it is not marketed or priced as a high-yield savings account. Its published rate has historically trailed the national average for competitive online accounts, based on third-party bank-rate aggregators. If maximizing yield is your goal, you will typically find better terms at an online-first bank or credit union.
That doesn’t mean Stock Yards Bank is a bad choice for everyone. For customers who value in-person service, a full suite of banking products, and a relationship with a Kentucky-based bank, the savings account may still make sense as part of a broader banking relationship — just not as the place to park an emergency fund purely for yield.
This article is an answer or purpose to what Scope Airs Bank actually offers on Basic Savings, what its price is and how to decide whether it suits your circumstances and improves your situation.
About the Author Asad is a personal finance writer focused on U.S. banking, savings products, and practical financial decision-making. He researches rates, fees, account requirements, and consumer-focused banking information using reputable financial and official sources.
What Stock Yards Bank Actually Offers on Savings
Stock Yards Bank & Trust, a subsidiary of Stock Yards Bancorp, Inc. (Nasdaq: SYBT), is a Louisville, Kentucky–based bank with roughly $9.31 billion in assets serving Louisville, Central and Eastern Kentucky, Indianapolis and Southern Indiana, and Cincinnati and Northern Kentucky markets Founded in 1904, it operates as a traditional community and private bank rather than an online-only savings specialist.
The bank’s core personal savings product is the Statement Savings account. According to the bank’s own account disclosures:
- Minimum opening deposit: $50
- Minimum daily balance to avoid fees: None required
- Withdrawal allowance: Three free withdrawals per statement cycle, with a $2 fee charged for each additional withdrawal
- Access: Online banking, mobile banking, online bill pay, and an ATM card are included
Stock Yards Bank does not publish a specific ongoing Statement Savings APY on its public rate pages, which is typical for many community banks — rates on basic savings accounts are often set locally and can vary by relationship, balance tier, or branch region. A third-party bank-rate research firm has reported the account’s savings rate at 0.30% APY, which it characterized as roughly in line with the national average for standard (not high-yield) savings accounts. Because bank rates change and this figure was not paired with a current effective date, treat it as directional rather than a guaranteed current rate, and confirm the exact APY directly with a Stock Yards Bank representative or the account disclosure before opening an account.
Stock Yards Bank also offers two products that pay meaningfully more than a basic savings account, though neither is technically a “high-yield savings account” in the way that term is used by online banks:
Premier Money Market Account. This account offers tiered interest rates that increase with balance size, FDIC insurance, and continued access to funds. It carries a $10 monthly service charge that can be waived by maintaining a qualifying minimum daily balance. A third-party aggregator has reported the bank’s highest money market tier around 1.00% APY, though — as with the savings rate — this figure should be confirmed directly with the bank, since money market tiers change based on balance and market conditions.
CD Specials. As of August 10, 2026, Stock Yards Bank advertised limited-time CD specials with rates up to 4.00% APY requiring a $10,000 minimum deposit to qualify for the promotional rate. Unlike a savings account, a CD locks your funds in for a fixed term, and early withdrawal generally triggers a penalty, though the bank’s disclosure notes that funds can typically be withdrawn without penalty after an initial six-day window following account funding.
It’s also worth noting that Stock Yards Bank’s Extreme Checking account — a checking product, not a savings account — currently advertises a notably high rate: 5.00% APY on balances between $0.01 and $10,000, and 0.10% APY on balances above $10,000, but only when the customer meets monthly qualifications such as ten qualifying debit card purchases, one direct deposit or ACH payment, and enrollment in e-statements. If those requirements aren’t met in a given statement cycle, the account reverts to a 0.10% base rate and loses ATM fee refunds for that cycle. Because it’s a checking account with an active-use requirement, it serves a different purpose than a savings account and isn’t a substitute for a dedicated emergency-fund savings vehicle — but it’s relevant context for readers who assumed “Stock Yards Bank’s best rate” referred to savings.
Why the Rate Gap Matters
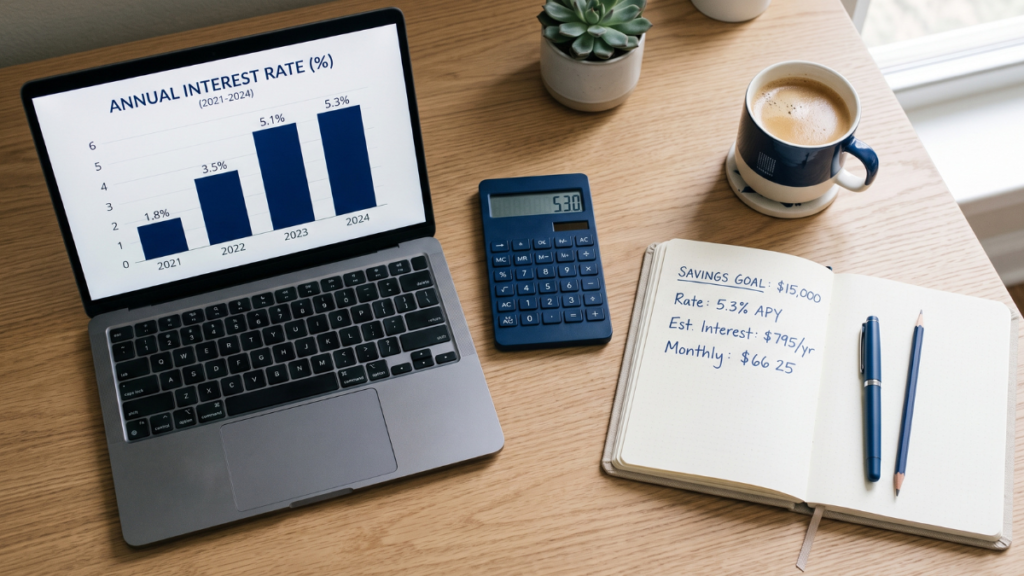
The difference between a 0.30% APY and a competitive high-yield savings rate is larger than it looks on paper. As of August 2026, the national average savings account interest rate was 0.38%, according to the FDIC Bankrate’s survey of more than 500 institutions put the national average savings yield at 0.63% APY as of August 20, 2026 Meanwhile, high-yield savings accounts averaged around 1.60% APY in August 2026, according to Curinos data, and the best high-yield savings accounts available nationally were paying up to roughly 4.21% APY as of August 21, 2026, according to NerdWallet’s research.
On a $10,000 balance held for one year, the difference between earning 0.30% and earning 4.00% is roughly $370 in interest — money that a basic savings account simply doesn’t pay, regardless of how good the bank’s service or reputation is otherwise. This is a hypothetical illustration, not a guarantee; actual returns depend on the exact APY, compounding frequency, and how long the balance is held, and rates on variable accounts can change at any time.
How Stock Yards Bank’s Savings Products Actually Work
Stock Yards Bank pays interest on savings balances the way most FDIC-insured banks do: interest accrues based on your daily balance and is credited to your account, typically monthly, according to the account’s disclosed rate. Because the Statement Savings account has no required minimum daily balance, you won’t be charged simply for letting your balance run low — but you also won’t be penalized into a higher rate for keeping more money in the account, since the bank has not published a tiered-rate structure for that product the way it has for its money market and checking accounts.
The three-free-withdrawal structure is a longstanding feature of many savings accounts and traces back to Regulation D, a Federal Reserve rule that historically limited certain types of withdrawals from savings accounts to six per month. The Federal Reserve amended Regulation D in 2020 to remove the six-transfer limit at the regulatory level, but individual banks — including Stock Yards Bank — remain free to set their own withdrawal limits and fees as a matter of account terms, which is why the $2 excess-withdrawal fee still applies here.
The Premier Money Market account works differently: it uses a tiered-rate structure, meaning your APY can increase as your balance crosses certain thresholds, and it requires either a qualifying balance or a $10 monthly fee. This is a common trade-off in money market accounts — the potential for a higher rate in exchange for a fee if you fall below the balance requirement.
It also helps to understand how interest actually accrues, since this applies to Stock Yards Bank’s accounts as well as any competitor’s. Most savings, money market, and CD accounts calculate interest daily based on your balance that day, then credit the accumulated interest to your account on a monthly cycle. You won’t see interest land in your account every single day, but it is being calculated every day behind the scenes. This has a practical implication: a large deposit that sits in the account for only a few days will earn only a few days’ worth of interest, not a full month’s worth. If you’re moving money between accounts to chase a better rate, timing matters — a balance that sits for the full statement cycle earns meaningfully more than one that’s deposited and withdrawn within the same cycle.
Important Factors Before You Open an Account
FDIC insurance. Stock Yards Bank & Trust is FDIC-insured</cite>, meaning deposits are protected up to the standard insurance amount of $250,000 per depositor, per insured bank, for each account ownership category. If you hold significantly more than that at one institution, you can structure accounts across ownership categories, or across multiple banks, to expand coverage — the FDIC’s Electronic Deposit Insurance Estimator can help calculate your specific coverage.
Geographic availability. Stock Yards Bank’s retail branch network is concentrated in Louisville, Central and Eastern Kentucky, Indianapolis and Southern Indiana, and Cincinnati and Northern Kentucky. Online account opening may still require a ZIP code within the bank’s service area, so this isn’t necessarily a nationwide option the way many online-only high-yield savings accounts are.
Fees beyond the excess-withdrawal charge. The bank’s broader account lineup carries some above-average fees relative to typical U.S. banks — for example, a third-party review noted the bank’s checking accounts carry a $5.00 monthly fee and a $36.00 overdraft fee, which is on par with the national average overdraft fee but still a cost worth factoring in if you plan to link savings to a checking relationship at the same bank.
No advertised ongoing high-yield savings tier. Unlike banks that market a specific “high-yield savings” product with a published, competitive APY, Stock Yards Bank does not currently advertise its Statement Savings account this way. If maximizing yield is your primary goal, this is the single most important thing to understand before opening the account.
Rates change. Every rate mentioned in this article is tied to a specific date because bank savings rates are variable and can change at any time, sometimes without much notice, based on Federal Reserve policy and each bank’s own funding needs. Always confirm the current rate directly with Stock Yards Bank before making a decision.
A Realistic Example
Suppose a saver has $15,000 in emergency savings and is deciding between keeping it at Stock Yards Bank’s Statement Savings account (hypothetically assumed at 0.30% APY) versus moving it to a competitive online high-yield savings account paying 4.00% APY. This is a hypothetical comparison using illustrative rates, not a guarantee of either bank’s actual current pricing.
- At 0.30% APY: $15,000 would earn approximately $45 in interest over one year, assuming no additional deposits or withdrawals and simple annual compounding for illustration purposes.
- At 4.00% APY: the same $15,000 would earn approximately $600 over one year under the same assumptions.
The roughly $555 difference doesn’t come from any additional risk — both accounts, assuming both banks are FDIC-insured, offer the same basic protection on the principal. The difference is purely a function of the interest rate the bank chooses to pay, which is often tied to whether the bank operates expensive physical branch networks (as Stock Yards Bank does) or runs a lower-overhead online model (as most top-yielding savings accounts do).
Benefits and Limitations
Potential benefits of banking with Stock Yards Bank for savings:
- Full-service, in-person banking with branches across its Kentucky, Indiana, and Ohio markets
- Low $50 minimum opening deposit and no minimum daily balance requirement on Statement Savings
- FDIC insurance up to standard federal limits
- Access to a broader banking relationship, including checking, CDs, money market accounts, mortgages, and private banking and wealth management services
- CD specials that have, at times, offered genuinely competitive promotional rates (up to 4.00% APY as of August 2026, with a $10,000 minimum)
- A long operating history dating to 1904 and a large regional presence, which some customers value for stability and local relationships
Limitations to weigh carefully:
- The core savings account is not priced to compete with high-yield online savings accounts
- No published ongoing high-yield savings tier or promotional APY for the Statement Savings product
- Limited free withdrawals (three per cycle) with a $2 fee for additional withdrawals
- Primarily a regional bank, which may matter if you don’t live near or bank within its Kentucky, Indiana, or Ohio footprint
- Broader fee structure on other account types (like checking) runs somewhat higher than average
Common Misconceptions
“High-yield” doesn’t automatically apply here. Some readers searching for “Stock Yards Bank high yield savings account” may assume the bank markets a specific high-yield product the way online banks do. Based on available information, it does not; its savings account is a standard product, and its more competitive rates are found in its CD specials and, situationally, its Extreme Checking account rather than in ongoing savings APYs.
A bank’s overall reputation isn’t the same as its savings rate. Stock Yards Bank has an established regional reputation and financial profile, but a strong institution is not the same thing as a competitively priced savings account. The two considerations — safety/reputation and yield — should be evaluated separately.
Checking account rates and savings account rates are different products. The 5.00% APY associated with Extreme Checking applies only to a checking account with monthly activity requirements, not to the bank’s savings account, and it drops sharply if those requirements aren’t met each cycle.
The advertised top rate isn’t always the rate you’ll actually earn — at any bank. This is a broader industry pattern worth understanding, not just a Stock Yards Bank issue: many banks that promote a headline high-yield rate only pay that rate up to a certain balance, or only above a minimum balance threshold, with a much lower rate applying outside that range. Before opening any savings account — at Stock Yards Bank or elsewhere — read the fine print on whether the advertised APY applies to your entire balance or only a portion of it, and whether there’s a minimum balance required to earn it at all.
Practical Considerations
If you’re already a Stock Yards Bank customer for checking, lending, or wealth management and want to keep your savings under the same roof for simplicity, the Statement Savings account is easy to open with a low $50 deposit and no ongoing balance requirement. If your priority is maximizing interest income and you don’t have another compelling reason to bank locally with Stock Yards Bank, it’s worth directly comparing the account’s current published rate (confirmed with a banker) against nationally available high-yield savings accounts before committing new deposits.
For larger sums you don’t need immediate access to, the bank’s CD specials may be worth a closer look, since promotional CD rates have periodically been competitive with — or better than — many high-yield savings accounts, in exchange for giving up some liquidity.
When Stock Yards Bank’s Savings Account May or May Not Make Sense
It may make sense if:
- You live in Stock Yards Bank’s Kentucky, Indiana, or Ohio service area and value in-person banking
- You’re consolidating accounts with an existing checking, lending, or wealth management relationship at the bank
- You don’t need to squeeze out the highest possible yield and prioritize convenience or relationship banking instead
- You’re specifically interested in a promotional CD rate rather than an everyday savings account
It may not make sense if:
- Your primary goal is maximizing interest earned on an emergency fund or short-term savings goal
- You don’t live in or bank within the Stock Yards Bank service area
- You’re comfortable managing an account entirely online and don’t need branch access
- You want a published, competitive ongoing APY without needing to call a banker to confirm current rates
It’s also worth stepping back to consider what a savings account — at Stock Yards Bank or anywhere else — is actually for. Savings accounts, including high-yield ones, are generally best suited to money you need to keep safe and liquid: an emergency fund, a house down payment you’ll need within a year or two, or cash set aside for a known short-term expense. They are not designed to build long-term wealth the way a diversified investment portfolio can over many years. A saver deciding between banks for an emergency fund should weigh rate and convenience; a saver with a multi-year time horizon and no near-term need for the cash may want to consider whether some of those funds belong in a different type of account altogether, separate from the savings-versus-savings comparison this article focuses on.
Key Takeaways
- Stock Yards Bank’s Statement Savings account is a standard, branch-based savings product, not an advertised high-yield savings account
- Its reported savings rate has historically trailed both the national average and, more significantly, top online high-yield savings accounts
- The bank’s more competitive rates, when available, tend to appear in CD specials and in its Extreme Checking account rather than in ongoing savings APYs
- All Stock Yards Bank deposit accounts are FDIC-insured up to standard federal limits
- Rates are variable and change over time — always confirm the current APY directly with the bank before opening or funding an account
- If yield is your top priority, compare Stock Yards Bank’s current published rate directly against competitive online high-yield savings accounts before deciding
Frequently Asked Questions
Q.1 Does Stock Yards Bank offer a true high-yield savings account?
Based on publicly available account information, Stock Yards Bank’s Statement Savings account is a standard savings product rather than a dedicated high-yield savings account. Its rate has historically been reported near the national average for basic savings accounts rather than in line with top online high-yield accounts.
Q.2 What is the minimum deposit to open a Stock Yards Bank savings account?
The Statement Savings account requires a $50 minimum opening deposit and has no required minimum daily balance afterward.
Q.3 Does Stock Yards Bank charge fees on its savings account?
The main fee to know about is a $2 charge for each withdrawal beyond three free withdrawals per statement cycle. There is no monthly maintenance fee disclosed for the Statement Savings account itself, though other Stock Yards Bank products, such as certain checking and money market accounts, do carry monthly service charges that can be waived under specific conditions.
Q.4 Is my money safe at Stock Yards Bank?
Yes. Stock Yards Bank & Trust is FDIC-insured, so deposits are protected up to $250,000 per depositor, per ownership category, in the event of a bank failure — the same standard protection offered at any FDIC-member bank.
Q,5 How does Stock Yards Bank’s rate compare to online banks?
As of August 2026, top nationally available high-yield savings accounts were paying up to roughly 4% APY, while the national average for standard savings accounts sat between 0.38% and 0.63% APY depending on the data source. Stock Yards Bank’s reported savings rate has generally aligned closer to the lower end of that range rather than the high-yield end.
Q.6 Are Stock Yards Bank’s CD rates better than its savings rates?
At times, yes. As of August 2026, the bank advertised CD specials up to 4.00% APY with a $10,000 minimum deposit — a meaningfully higher rate than its standard savings account, in exchange for less liquidity and, potentially, an early withdrawal penalty if funds are removed within the first six days of funding.
Q.7 Can I open a Stock Yards Bank savings account if I live outside Kentucky, Indiana, or Ohio?
Stock Yards Bank’s branch network and, in some cases, its online account-opening tools are tied to its regional service area. If you’re outside that footprint, confirm eligibility directly with the bank before assuming you can open an account.
Q.8 What are good alternatives if I want a higher savings rate?
Online-first banks and credit unions frequently offer significantly higher APYs than regional, branch-heavy banks because they carry lower overhead costs. When comparing alternatives, look beyond the headline APY to also check minimum balance requirements, monthly fees, FDIC or NCUA insurance status, and how easily you can transfer funds in and out.
Conclusion
Stock Yards Bank & Trust offers a straightforward, low-barrier savings account with a $50 minimum deposit and no ongoing balance requirement, backed by standard FDIC insurance. But based on the information the bank and independent researchers make available, it is not currently positioned as a high-yield savings option — its reported rate trails both the national average for basic accounts and, more substantially, the top online high-yield accounts available in 2026. The most important thing to do before opening or funding an account is to confirm the bank’s current, exact APY directly, since rates change and are not always published in real time on general account pages. If your main objective is growing an emergency fund or short-term savings as efficiently as possible, it’s worth comparing that confirmed rate against competitive online alternatives before deciding where your money will work hardest.
Financial Disclaimer: This article is for educational and informational purposes only and should not be considered personalized financial or investment advice. Interest rates, fees, and account terms mentioned are subject to change and were accurate as of the dates cited; always confirm current rates and terms directly with Stock Yards Bank & Trust or any other financial institution before opening an account. Financial decisions should be based on your individual circumstances and, when appropriate, discussed with a qualified financial professional.